
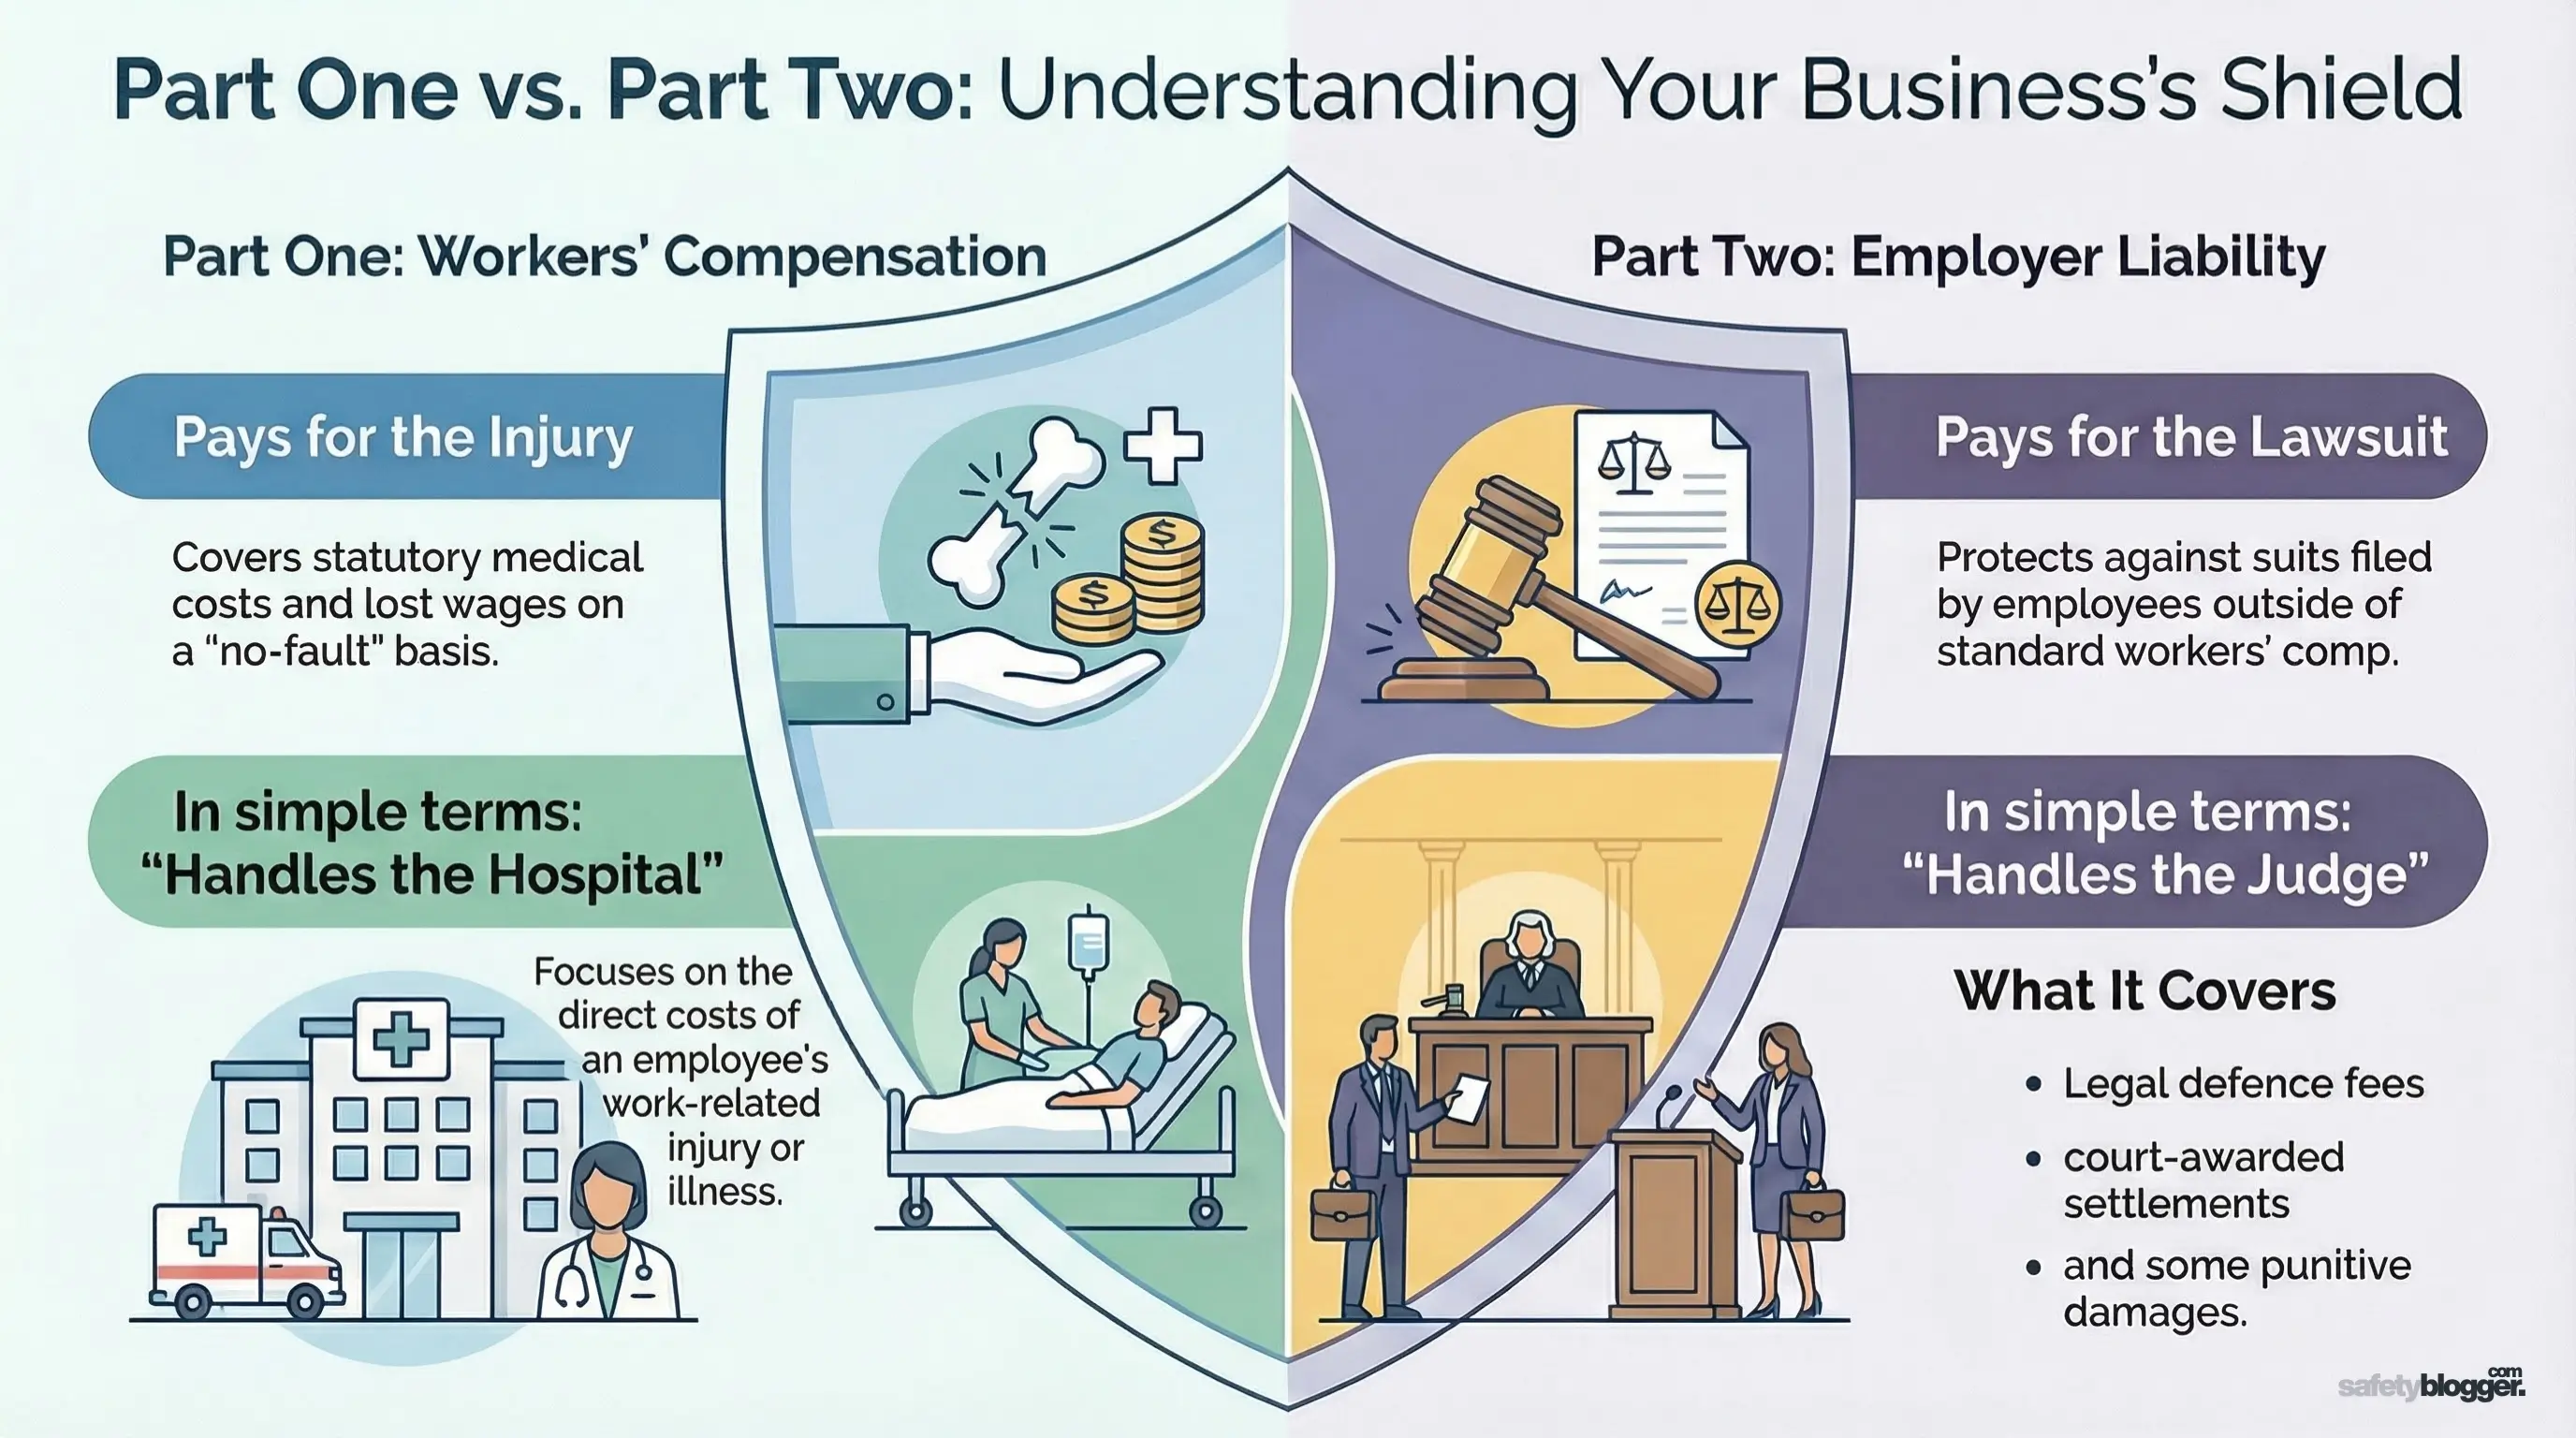
Employers liability is like the fine print in a dating app bio. It says, “I’m not responsible for anything… except when I am.” This coverage kicks in when an employee tries to sue the company outside of workers’ comp. For example, if your boss knew the ladder was broken and told you to use it anyway—that’s not “carelessness,” that’s gross negligence. Workers’ comp doesn’t touch that.
Or consider a third-party lawsuit. You’re a delivery driver, and an idiot in a BMW sideswipes your van. You can sue the BMW owner. But guess what? Your employer might be jointly sued for faulty training or a broken brake system. That’s when employers liability insurance pays for the company’s legal defense and any settlement—not your medical bills. Confusing? Stick with me.
 PPT - Insurance & Risk Management 101 PowerPoint Presentation, free
Key Difference #1: Who Gets Paid?
Workers’ comp pays you directly, no questions asked. Employers liability pays your employer’s legal fees and damages if you get a lawyer. Think of it as the difference between getting a pizza delivered and paying for the delivery guy’s car insurance after he crashes into your mailbox. One is your pizza; the other is his mess.
Key Difference #2: Pain and Suffering
Workers’ comp never covers pain and suffering. Ever. But employers liability can—if your case goes to court and you prove your employer was reckless. Imagine losing a thumb in a machine that your boss disabled the safety guard on. Workers’ comp pays for surgery and lost wages. Employers liability could pay you an extra $100,000 for the trauma. That’s the big money Dave was dreaming about.
Key Difference #3: The “Intentional Act” Trap
Here’s the really weird part: if your employer intentionally hurts you—like, shoves you into a freezer for being slow—workers’ comp does not apply. You can sue them directly. Employers liability will then cover the lawsuit, but only if the insurance company doesn’t scream “exclusion.” If the act is criminal, the policy might say, “Nope, that’s on you, boss.” So employers liability is not a blank check for tyrants.
 What Is Employer Liability Insurance? Coverage & Risk Explained

