
Out-of-Pocket costs usually come in three flavors: deductibles, copays, and coinsurance. They’re like that friend trio where one is dramatic, one is chill, and one is always calculating the bill. Let’s break them down so you don’t need a decoder ring.
First up: the deductible. This is the amount you must pay every year before your insurance starts covering stuff. It’s like a video game boss—you have to defeat it (pay it) to unlock the next level. For health insurance, it might be $1,500 or $5,000. For car insurance, it’s the cash you pay after an accident before the company fixes your bumper. The higher your deductible, the lower your monthly premium. It’s a trade-off: pay now or pay later.
Next is the copay. This is a flat fee you pay for a specific service, like $20 for a doctor’s visit or $10 for a prescription. It’s the insurance version of a “convenience fee.” You walk in, you hand over a twenty, and you get to see a professional who tells you to drink more water. Copays usually don’t count toward your deductible, but they do count toward your annual OOP maximum.
Finally, there’s coinsurance. This one’s a bit trickier. It’s a percentage you pay after you’ve met your deductible. Say your plan has 20% coinsurance. That means you pay 20% of the bill, and insurance pays 80%. If your hospital stay costs $10,000, you’re on the hook for $2,000. Ouch. But don’t panic—there’s a safety net.
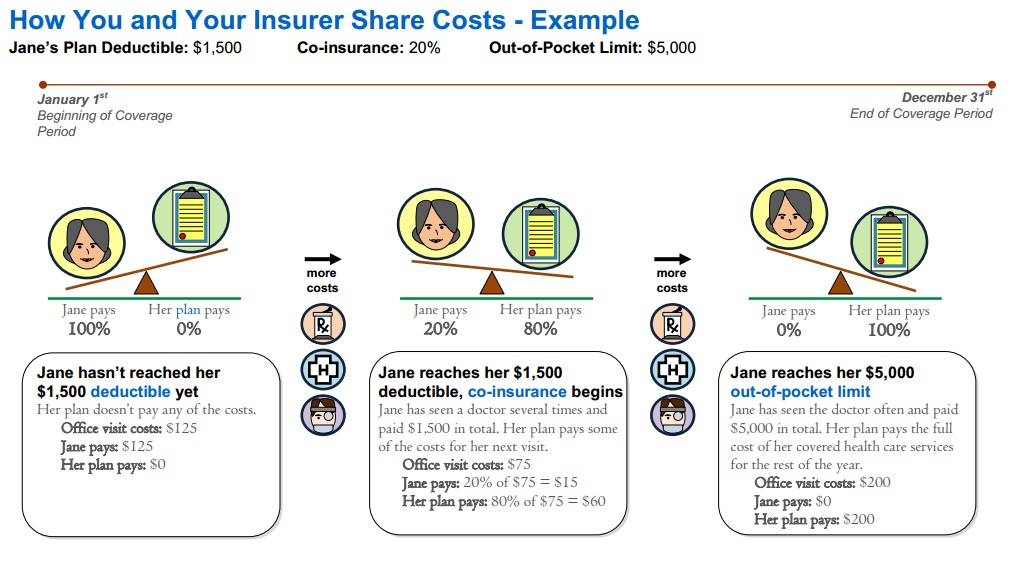 OOP Out of Pocket Maximum calendar year deductible meanings
The Magic Number: OOP Maximum
Every insurance plan has a maximum out-of-pocket limit. This is the absolute most you’ll pay in a year for covered services. Once you hit that number, insurance covers everything at 100% (for the rest of the year). It’s like a financial force field. For 2026, the federal limit for health plans is around $9,450 for individuals and $18,900 for families. So even if you get hit by a meteor and need six surgeries, you won’t pay a penny more after that cap. Phew.
Here’s the hidden gem: your deductible, copays, and coinsurance all count toward that maximum. But monthly premiums? Nope, those are separate. It’s like a loyalty card for paying medical bills—collect enough stamps, and you get a free rest of the year. Well, “free” in a relative sense, since you’ve already paid thousands.

