
Let’s talk culture: the word “foreclosure” sounds like a villain from a dystopian novel—think Lord Voldemort meets a bank teller. But for VA borrowers, it’s often avoidable. The VA’s database shows that over 90% of VA loans in trouble are resolved without foreclosure through loan modifications, repayment plans, or partial claims. That’s a 9-to-1 odds ratio that would make any Vegas dealer raise an eyebrow.
Practical tip three: use the VA’s “Call to Service” hotline (1-877-827-3702) before you call a lawyer. The VA can mediate between you and the lender, often squeezing out a better deal. Think of it as having a seasoned negotiator on speed dial, like Harvey Specter from Suits, but without the expensive suits. And if you’re feeling overwhelmed, remember: a foreclosure on a VA loan takes at least 12 months to complete—that’s plenty of time to craft an exit strategy.
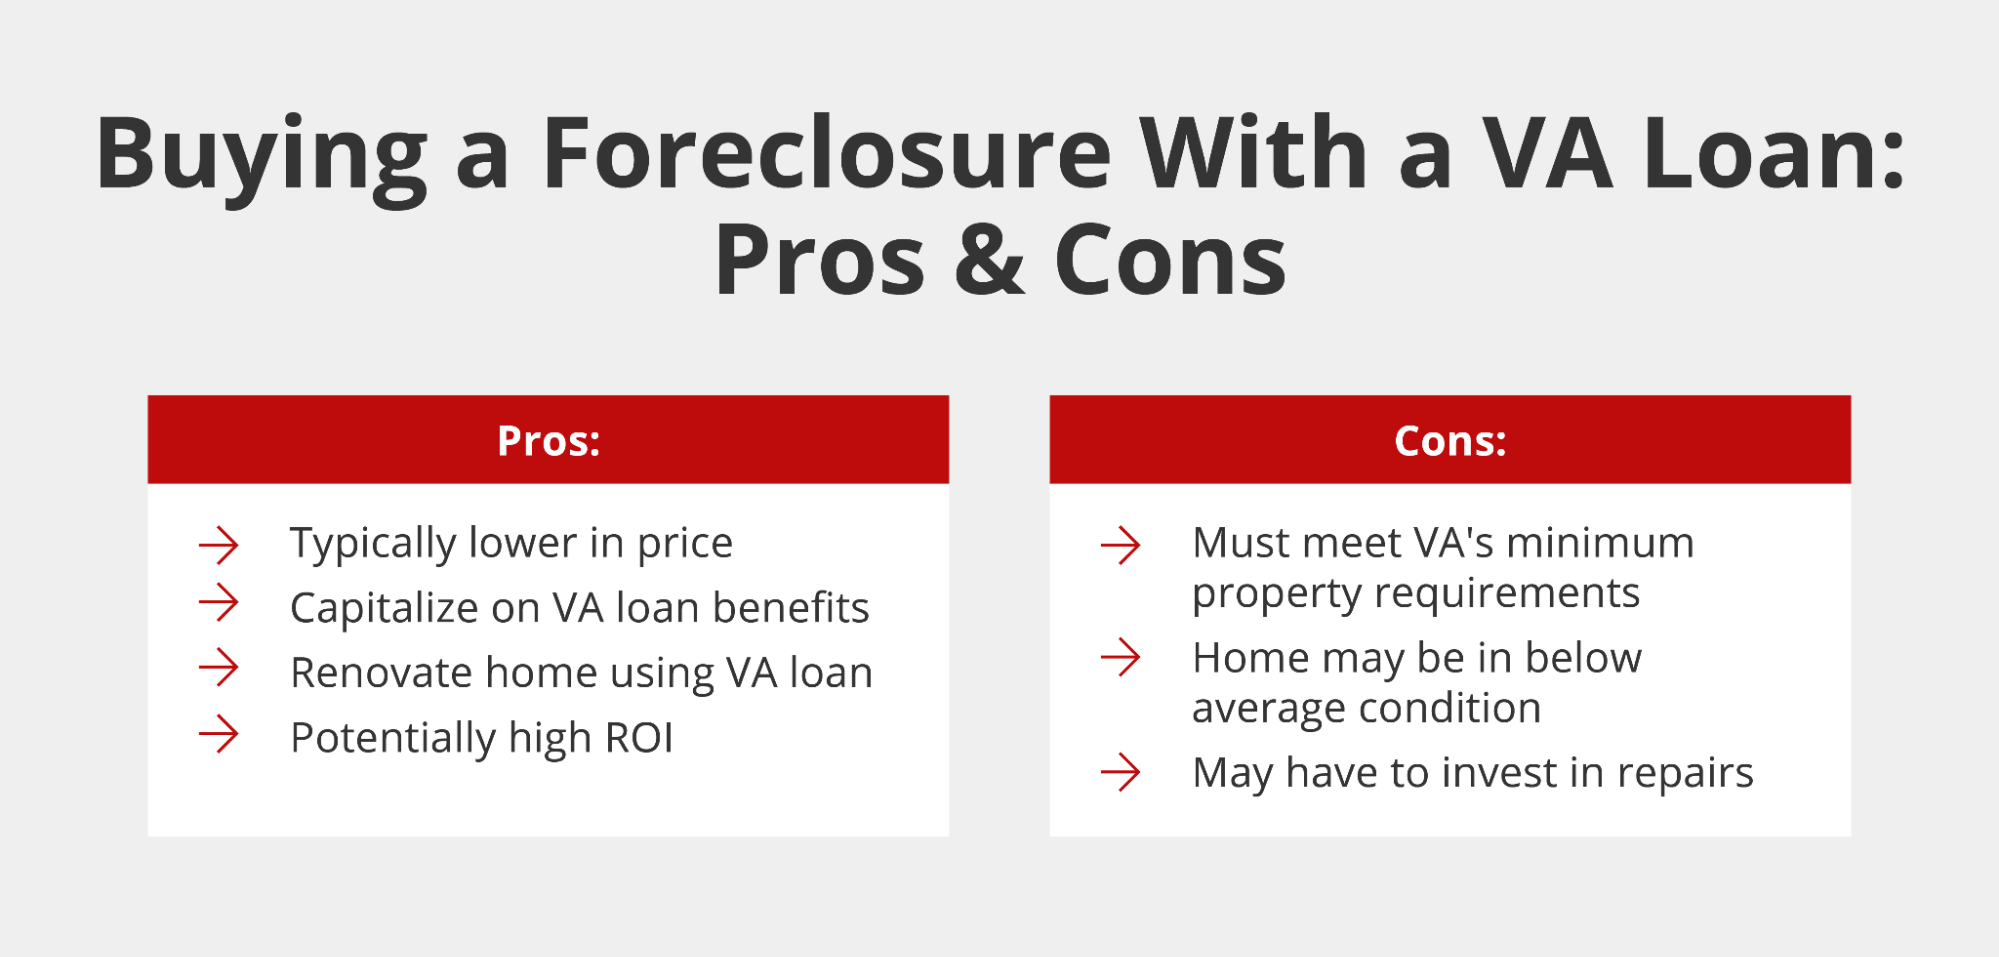 Can You Buy a Foreclosure Home With a VA Loan? | Griffin Funding
The “Lean In” Moment
Imagine you’re at a coffee shop, staring at a latte art that looks like a house. Could you lose that house? Maybe. But the VA loan structure is designed to keep you in the game, not out of it. The government wants you to succeed because your mortgage isn’t just a debt—it’s a symbol of the country’s promise to you. So, when the market dips or life throws a curveball, you’re not alone; you’ve got Uncle Sam in your corner, cheering you on like a hype man at a Beyoncé concert.
Final thought: homeownership is less about having the perfect roof and more about having a resilient foundation. Your VA loan is that foundation—built with flexibility, backed by a community, and designed to bend without breaking. The next time you see a foreclosure sign on the news, don’t panic. Instead, pour yourself a coffee, take a breath, and remember: you’re not a statistic from a Ryan Reynolds meme; you’re a person with a very powerful piece of paper.
Life lesson: Just like your favorite pair of combat boots, a VA loan can take a beating—but it always comes with a way to lace up again.

