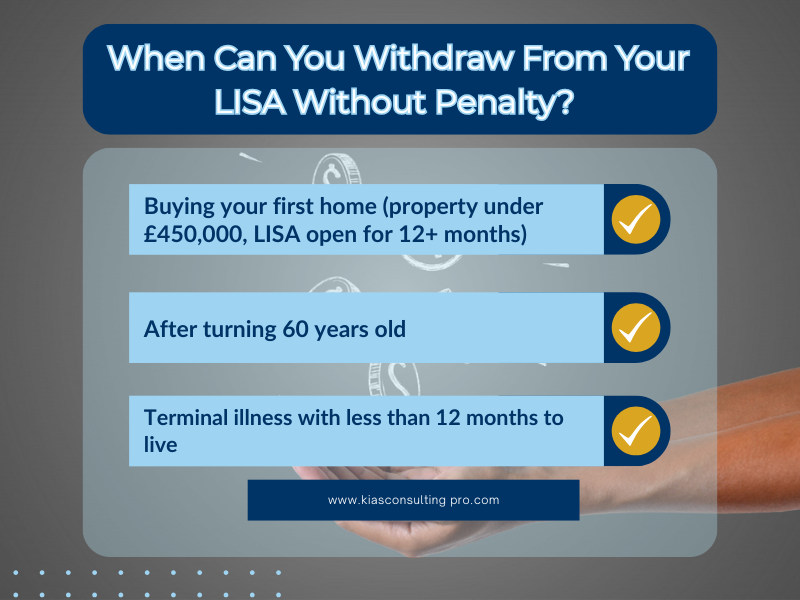
You can withdraw your money without penalty in exactly two situations. First, if you’re using it to buy your first home (up to £450,000). The property has to be in the UK, and you need to have held the account for at least 12 months. Think of it as a 12-month waiting period to prove you’re serious.
The second free pass is when you turn 60. That’s right — you can then take everything out, including the government bonus and any growth, with zero fees. It becomes a lovely, tax-efficient retirement top-up. You can literally do whatever you want with it at that point: buy a canal boat, travel the world, or hoard it like a dragon. No questions asked.
There’s also a third, less happy free pass: if you are terminally ill and expected to live less than 12 months. This is a genuine, no-nonsense exception. It’s the government’s way of saying, “Okay, life happened. Take your money.”
The Ugly Exit: What Happens If You Withdraw Early
Here’s where Dave got burned. If you take money out for any other reason — like a car, a holiday, or just because you’re bored — you pay a 25% withdrawal penalty. Sounds simple, right? It’s not. That 25% doesn’t just take back the government bonus; it eats into your own savings too.
 Lifetime ISA
Let’s do the maths (I promise it’s quick). You put in £4,000. The government adds a 25% bonus, so you have £5,000. You withdraw early. The penalty is 25% of the total value: £1,250. You get back £3,750. That means you just lost £250 of your own money, plus the entire bonus. It’s a double gut-punch.
So the penalty isn’t just “giving back the bonus” — it’s a punishment withdrawal. The government designed it to hurt, because they really don’t want you to do it. And you shouldn’t, unless you absolutely have to. Dave’s sports car now sits in his driveway, and he still winces every time he looks at his bank statement.
The One Weird Edge Case: Death and Disability
If you die before 60, your Lifetime ISA gets passed to your estate or your beneficiary. They can withdraw the full amount — including the bonus — without any penalty. It’s a cruel mercy, but at least the taxman doesn’t take a cut from your loved ones.
Similarly, if you become permanently disabled (as defined by HMRC, which is strict), you can withdraw penalty-free. You’ll need a doctor’s note and a fair bit of paperwork, but the money is yours without the 25% hit.
 Lifetime ISA for retirement | Hargreaves Lansdown

